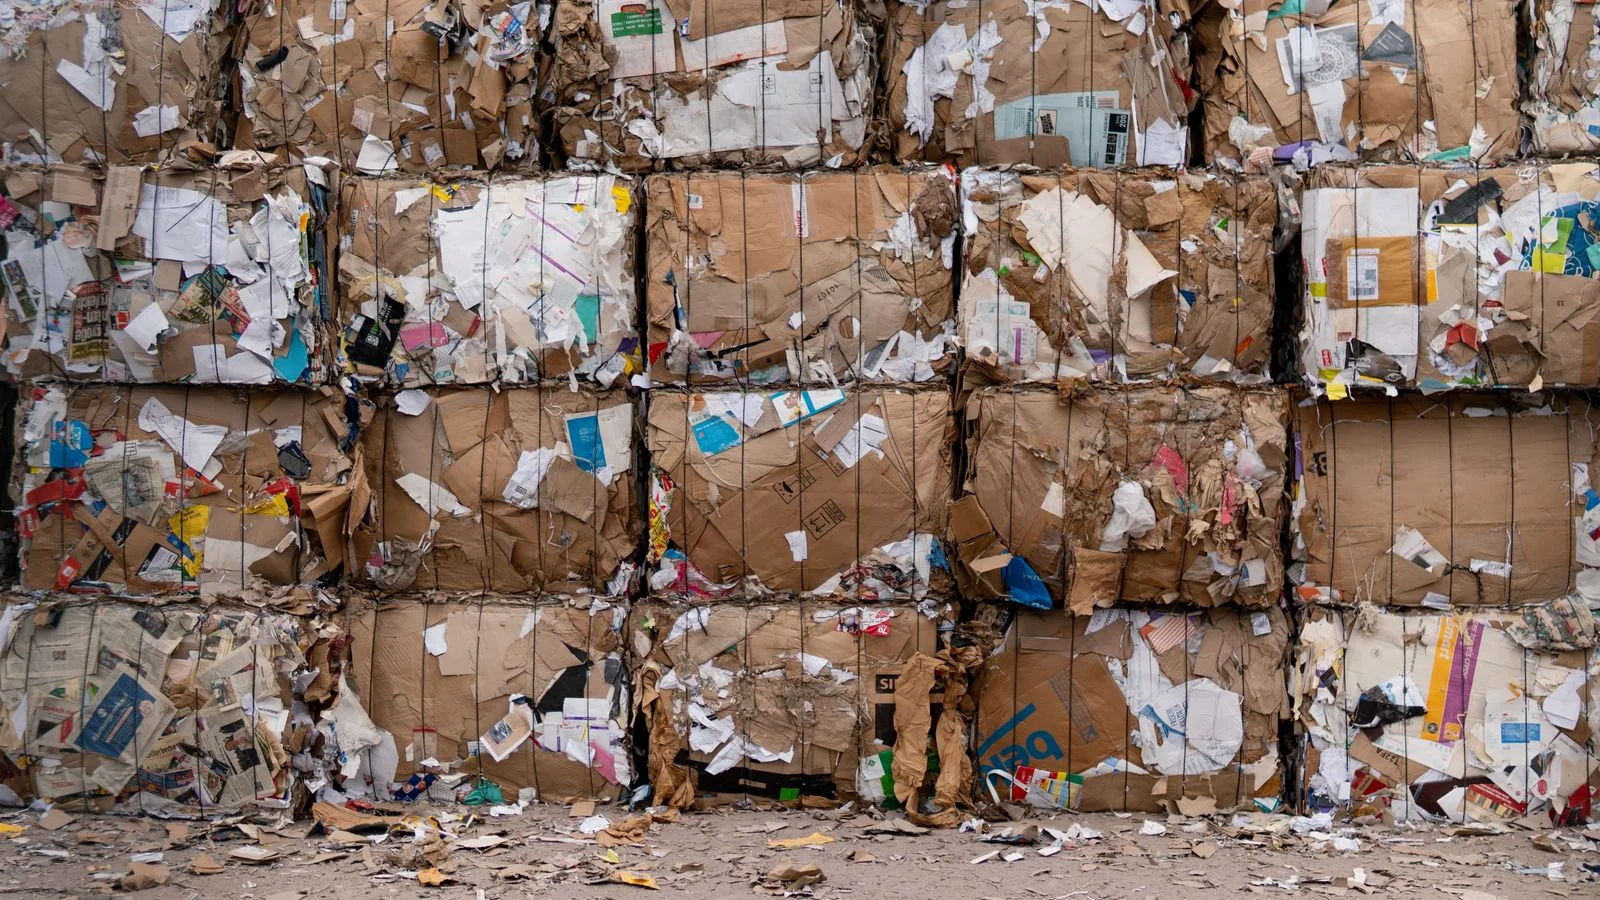
The last full national recycling rate the U.S. Environmental Protection Agency published was 32.1 percent, for 2018, and the number had barely moved in a decade. Since then the public conversation about recycling has been dominated by people outside the industry: investigative reporters showing that most plastic is not recycled, environmental groups calling the chasing-arrows symbol a fraud, and a growing share of residents who have concluded that the blue bin is theater. The people who actually run recycling facilities, who know exactly which materials have end markets and which do not, have been almost silent in that conversation, and the silence has been read as confirmation.
That is the opening for thought leadership for recycling companies. The industry’s critics have been effective because they are the only ones explaining anything. An operator who explains the business in public, with real numbers, including the uncomfortable ones, becomes the source reporters, municipalities, and commercial customers trust, and there is almost no competition for the role.
The recycling rate has not moved and nobody is explaining why
Ask a city council member why the recycling rate is stuck and they will say residents do not participate. Ask a resident and they will say it all goes to the landfill anyway. Ask a reporter and they will cite the plastics investigations. Each of those is partly true and none of them is the explanation an operator would give, which involves commodity prices, contamination, the collapse of export markets after 2018, the difference between collection and actual recovery, and the fact that aluminum and cardboard have strong end markets while mixed plastics mostly do not.
Nobody outside the industry knows that, because nobody inside the industry has said it in public in a form a reporter can quote. The trade press covers it for the trade. The general public gets the investigations and the press releases, and the press releases lose.
Thought leadership in this industry is not about vision statements. It is about being the person who can explain, in one paragraph a council member can repeat, why a ton of mixed paper was worth one thing in 2017 and something very different in 2019, what that did to the city’s contract, and what the city can do about it. The operator who does this becomes the person the council calls before the next rate hearing, the person the reporter calls before the next investigation, and the person the commercial customer calls before the next contract.
The Bale Price Brief
Here is the framework, and it is the single most effective piece of thought leadership a recycling company can publish. The Bale Price Brief is a monthly, one-page, plain-language report on what the top five recovered commodities in the region are worth, why each one moved, and what it means for the municipalities and businesses the facility serves.
The five are usually old corrugated cardboard, mixed paper, PET, natural HDPE, and aluminum cans, though a facility should pick the five that matter most to its own customers. For each, the brief gives the regional price per ton or per pound this month, the change from last month and from a year ago, and two sentences on the driver: mill demand, export policy, virgin resin pricing, a new domestic plant coming online, a seasonal swing in cardboard from the holiday shopping cycle. Then one paragraph on what the movement means for a municipal contract with revenue share, and one for a commercial customer with a rebate.
No other organization in a region publishes this. The trade price indexes exist, but they are behind paywalls and written for people who already understand the market. The Bale Price Brief translates them for the people who sign contracts and write stories. Within a few months of publishing it, the facility’s general manager is the person every reporter in the region emails when recycling is in the news, because the reporter has the brief in their inbox and the brief has a name on it.
Here is what one entry looks like, so the format is concrete. “Old corrugated cardboard, regional: $X per ton this month, up from last month and down from a year ago. Mill demand in the Southeast picked up after two lines came back from maintenance, and holiday shipping volume is starting to show in the inbound stream. For cities with revenue-share contracts, this month’s cardboard price adds back some of what mixed paper took away. For commercial accounts on a rebate, expect the cardboard line on the statement to move up slightly.” Five of those, one page, with the general manager’s name and the date at the top. The number is filled from the index the facility already subscribes to. The two sentences of explanation are the part nobody else writes, and the part that makes the general manager the market’s interpreter.
The brief also creates a record. After twelve issues, the facility has the only public, plain-language history of regional recovered commodity prices, and that history gets cited: by the reporter writing the year-end recycling story, by the consultant preparing a city’s RFP, by the analyst at an acquirer valuing the facility, and by the AI assistant asked what happened to recycling revenue in the region. Thought leadership for recycling companies is mostly a matter of being the one who wrote things down.
Publish it on the facility’s site as a page, not a PDF, so search engines and AI assistants can read it. Send it by email to every municipal partner and commercial account. Post the headline number on LinkedIn with a two-sentence explanation. Keep every past issue online, because a year of briefs is a dataset that gets cited.
Where to publish
The facility’s own site is first, because it is the only place the company controls and the only place an AI assistant can be sure the content came from the operator. Every brief, every explainer, and every talk should live there with a date and an author.
LinkedIn is second, for municipal staff, commercial sustainability managers, consultants, and trade reporters, all of whom are there and none of whom are reading trade press regularly. Weekly posts drawn from operations, a photo of a contaminated bale with the cost, a note on a new end market, a paragraph on a policy change, build the audience that reads the monthly brief.
The regional press is third, and the path is the brief. Send it to the reporter who covered the last recycling story with a note offering to explain any of it. When the next story comes, the reporter calls. One quote in the metro daily, on the record, explaining why the city’s recycling revenue fell, is worth more than anything the company could publish itself, because it is a third-party source that Google and AI assistants treat as evidence the operator is the authority. Run the general manager’s name through the AI Authority Score tool on this site before and after the first quote and watch what changes.
The trade press is fourth. Resource Recycling, Waste Dive, and Recycling Today all run operator commentary, and a bylined piece on regional end markets or contamination economics puts the operator in front of the whole industry, including the municipal consultants who write RFPs and the acquirers who buy facilities.
Council meetings and state recycling conferences are fifth. A general manager who presents the Bale Price Brief to a council once a year, or speaks on a state association panel about contamination, is heard by the people who decide contracts and policy. These rooms are small and the competition for the microphone is nonexistent.
What to say when the numbers are bad
The hardest part of thought leadership for recycling companies is that the honest story is often unflattering. Mixed plastics have weak end markets. A share of what residents put in the bin is not recycled. Contamination rates are high. Some programs cost cities more than landfilling would. An operator who publishes only good news is not trusted, and an operator who says nothing is assumed to be hiding the bad news that the investigations already exposed.
The answer is to say it first, with specifics, and with the distinction the critics miss. Aluminum and cardboard are recycled at high rates into products people use, and the economics work. PET and HDPE bottles have real domestic markets that are growing. Mixed plastics numbered three through seven mostly do not, and the honest position is to tell residents which is which and to advocate for the policies, such as extended producer responsibility and minimum recycled content, that would change the economics. An operator who says this becomes the credible voice on both sides of the argument, because the environmental groups hear an ally on policy and the municipalities hear a partner who tells the truth.
There is a specific way to handle the plastics question, because it is the one every reporter asks and the one most operators fumble. The wrong answer is defensive: recycling works, the critics are exaggerating, keep putting everything in the bin. The wrong answer in the other direction is capitulation: plastics recycling is a myth, sorry. The right answer is the operator’s answer, with the facility’s own numbers: here is what we received in PET last year, here is what percentage went to a domestic reclaimer, here is who bought it and what they made from it, here is the mixed-plastic tonnage that had no buyer and where it went, and here is what would change that. An operator who can say that on the record, with tonnage, is the only credible voice in the room, because everyone else is arguing from national estimates and the operator is reporting from the scale house.
The same applies to contamination. The honest number for many facilities is uncomfortable, and the temptation is to leave it out of the brief. Put it in. A facility that publishes its inbound contamination rate, the cost of it, and what it is doing with its municipal partners to bring it down is telling the market that it measures what matters. The municipalities read that as competence. The reporters read it as a source who does not spin. The acquirers read it as a management team that knows its own numbers. Nobody reads it as weakness, because the alternative, silence, has already been interpreted as having something to hide.
Say it in the brief, say it to the reporter, say it at the council meeting. The company that explains the gap between collection and recovery, in its own market, with its own numbers, owns the conversation that the critics have been running unopposed.
The operators who start explaining now will be the ones defining what recycling means in their regions when the next round of packaging laws arrives and every city needs someone to tell them what the new rules will do to the bin.